Business
How to Protect Your UK Business From an HMRC Compliance Check

A brown envelope arrives with HMRC printed on the front. Most business owners feel their stomach drop before they have even opened it. The immediate assumption is that something has gone wrong, that penalties are coming, and that the next few months are going to be expensive and stressful. That reaction is understandable but it is also rarely accurate. Experienced tax investigation advisors will tell you the same thing: an HMRC compliance check is not automatically a sign of wrongdoing, and how you respond in the first few days matters far more than most people realise. This guide explains why compliance checks happen, what HMRC is actually looking for, and how to protect your business both before and after that letter arrives.
Why HMRC Compliance Checks Matter?
HMRC’s approach to compliance has changed significantly in recent years. The days of purely random selection have not disappeared entirely, but the majority of compliance activity is now data-driven. HMRC uses sophisticated analytics, cross-references information from multiple sources banks, Companies House, land registries, digital platforms and compares your filings against industry benchmarks and third-party data it already holds.
That means even well-run businesses with clean records can attract a compliance check through no fault of their own. A data mismatch between what you reported and what a third party reported to HMRC can trigger contact regardless of whether the underlying figures are correct.
Compliance Check vs Tax Investigation
| HMRC Compliance Check | Tax Investigation |
| Routine review of specific areas | Deeper examination of overall tax affairs |
| Often focused on a single issue | Can cover multiple taxes and multiple years |
| Frequently preventative in nature | Usually triggered by identified concerns |
| Typically shorter in duration | Can run for one to three years or more |
A compliance check can escalate into a full investigation if HMRC finds material discrepancies, discovers records are incomplete, or identifies behaviour that suggests the problem runs deeper than a single filing period. That escalation is not inevitable but it is avoidable, and the way you respond determines which direction the process goes.
Why HMRC May Contact Your Business?
Selection is not always what people expect. Some reviews are sector-specific; HMRC runs targeted campaigns against industries it considers higher-risk, which means a perfectly compliant business in construction, hospitality, or e-commerce can receive a compliance letter simply because of its sector classification.
Other triggers are more specific. Unusual expense claims relative to turnover, VAT return figures that fluctuate significantly between periods, payroll inconsistencies, repeated late filings, and mismatches between income declared and lifestyle indicators visible through third-party data are all known selection factors.
Online income is a growing area of focus. HMRC now receives data from digital platforms eBay, Etsy, Airbnb, Amazon under updated reporting requirements, and any business or individual with significant online sales that does not appear on a self-assessment return or corporation tax filing will eventually attract attention.
The honest answer to “why me?” is often simply this: a data point somewhere did not align, and HMRC wanted to understand why.
What HMRC Is Really Looking For?
Understanding the focus areas helps businesses prepare genuinely useful responses rather than producing mountains of paper that do not address the actual question.
Income reporting is the starting point. HMRC wants to confirm that all income has been declared including cash income, income from secondary sources, overseas income, and digital platform income. Business expenses come next, with particular focus on whether claimed expenses are genuinely business-related and properly evidenced.
VAT accuracy is one of the most frequently reviewed areas, especially for businesses with complex supply chains or mixed VAT liability. Payroll compliance covers PAYE deductions, benefits in kind, National Insurance treatment, and whether contractors have been correctly classified. Director loan accounts attract specific scrutiny because they are frequently misunderstood and often create unexpected tax liabilities.
Record-keeping standards underpin all of it. HMRC cannot assess figures it cannot verify, and a business that cannot produce supporting documentation for its claimed figures is in a significantly weaker position than one that can.
The First 48 Hours After Receiving an HMRC Letter
This is where most unforced errors happen, and most of them come from reacting too quickly rather than too slowly.
Step 1: Read the letter carefully. Identify precisely what HMRC is asking which tax, which period, and exactly what information has been requested. The scope matters enormously. A compliance check on a specific VAT period requires a very different response than one covering three years of corporation tax.
Step 2: Stay calm. Panicked responses that volunteer information beyond what was requested, or that make assumptions about what HMRC already knows, consistently create problems that a measured response would have avoided.
Step 3: Gather relevant records. Pull together the documentation that relates to the specific period and area under review. Organise it chronologically and review it before you send anything.
Step 4: Look for inconsistencies yourself. Before responding, review the records to identify whether there are any discrepancies that HMRC might find. Discovering a problem yourself, before HMRC raises it, almost always produces a better outcome than waiting for them to find it.
Step 5: Create a response timeline. HMRC’s deadlines are not flexible. Missing one signals disorganisation at best and non-cooperation at worst both of which give HMRC reasons to look harder.
Step 6: Decide whether you need specialist support. For a straightforward, single-issue compliance check with clean records, a prepared business owner can often manage the process adequately. For anything more complex, the equation changes.
Hidden Errors HMRC Frequently Finds
Compliance checks often surface problems the business owner was not aware of not because of dishonesty, but because of misunderstanding or poor process.
Incorrect expense claims are the most common. Personal expenses coded as business costs, a family dinner claimed as a client meeting, home utility bills put through the company are visible to HMRC through lifestyle data and frequently appear in compliance checks. Director loan accounts are another consistent finding: amounts drawn without correct documentation, without interest charged where required, or without repayment arrangements that would satisfy HMRC’s requirements.
VAT calculation errors on mixed-supply businesses catch many firms off guard. A business selling both standard-rated and exempt supplies that applies the wrong apportionment methodology may have been filing incorrect returns for years without realising it. CIS deductions the Construction Industry Scheme generate frequent compliance issues around contractor versus subcontractor classification and the correct deduction rates applied.
Poor supporting documentation is the thread connecting most of these. A figure on a tax return without a receipt, invoice, or contract to support it is not a figure HMRC has to accept.
How to Reduce the Risk of HMRC Scrutiny?
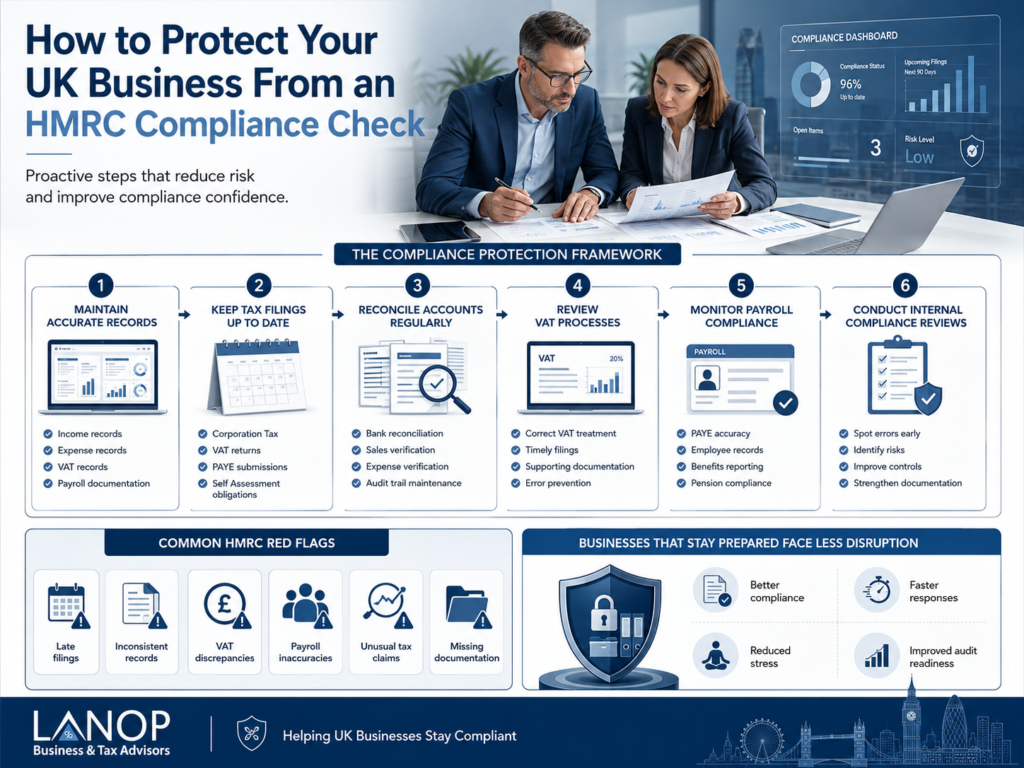
Prevention is considerably less expensive than response. Several practical steps reduce the likelihood of compliance contact and, if contact does happen, put the business in the strongest possible position.
Reconcile accounts regularly monthly at minimum. Discrepancies identified and corrected during the year are far less damaging than ones that accumulate unnoticed into a pattern HMRC finds in a compliance review. Maintain VAT accuracy by reviewing each return before submission rather than treating it as a mechanical process. Keeping business and personal finances strictly separate is a common area of failure for sole traders and owner-managed companies alike.
Retain supporting documentation for every material transaction. HMRC expects records to be kept for at least six years for companies and five for individuals. An internal compliance review conducted annually comparing filed figures against underlying records identifies issues while correction is still straightforward.
File returns on time, every time. Repeated late filing creates a compliance profile that attracts attention, and the penalties accumulate faster than most businesses expect.
The Mistakes That Make Compliance Checks Worse
Several behaviours consistently escalate what could have been a routine, resolvable check into something considerably more serious.
Ignoring HMRC correspondence is the worst. HMRC does not interpret silence as an answer.it interprets it as non-cooperation, which gives the authority grounds to use more formal powers. Missing a response deadline can convert a compliance check into a formal investigation with significantly expanded scope.
Sending information without reviewing it first is a close second. Documents that contradict each other, or that raise new questions HMRC was not previously asking, extend the timeline and expand the scope of review.
Guessing figures rather than verifying them creates inconsistencies in the record that are harder to explain as the process develops. Assuming small errors do not matter is a version of the same mistake HMRC’s systems are designed to detect patterns, and small consistent errors often indicate a systematic problem rather than an isolated one.
Waiting too long to seek advice is a pattern that experienced practitioners see repeatedly. By the time a business owner realises the compliance check has become something more serious, some options that were available earlier have already closed.
What Happens During an HMRC Compliance Check?
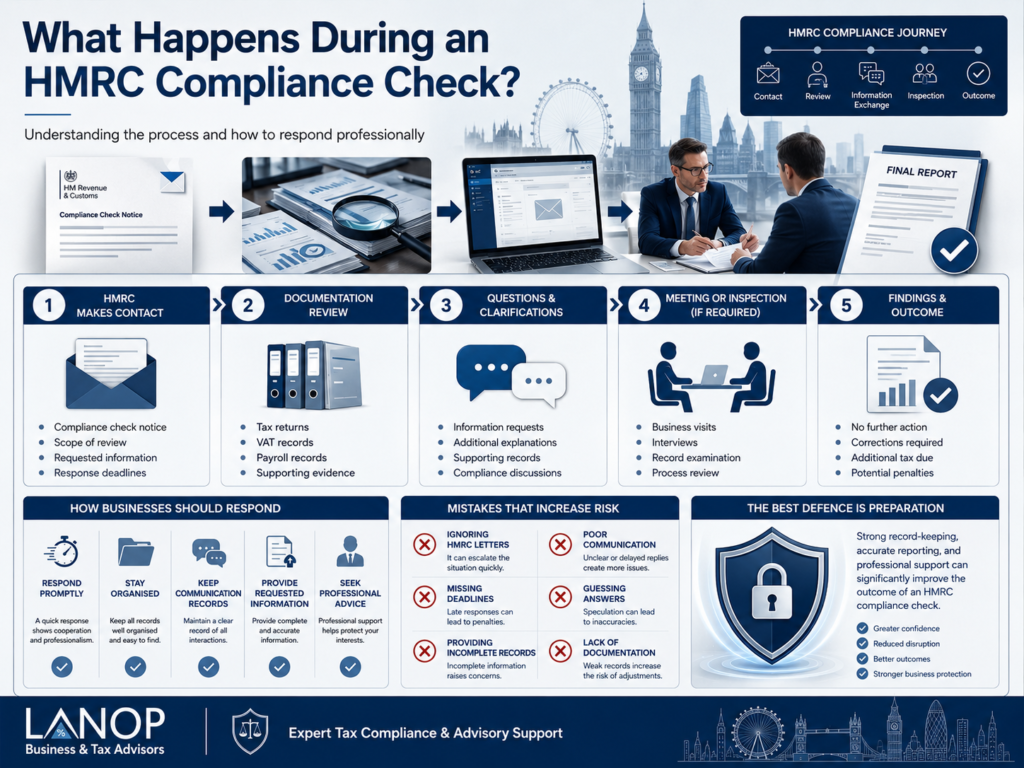
The process follows a broadly consistent structure. Initial contact arrives by letter, identifying the area under review and requesting specific information within a defined timeframe. An information-gathering stage follows, during which HMRC reviews what has been provided and may ask follow-up questions. In some cases, HMRC requests a site visit to inspect records directly; these are not mandatory to accept without prior agreement, and the scope of any visit should be clarified before it takes place.
A resolution stage eventually arrives, resulting either in HMRC confirming that the matter is closed, issuing an assessment for additional tax, or in more serious cases escalating to a formal investigation. Throughout the process, the quality and speed of responses directly influences the timeline and, often, the outcome.
What HMRC Can and Cannot Do?
HMRC has significant powers, but they are not unlimited. It can request documents and records, require answers to written questions, conduct inspections, and in certain circumstances access bank account information. What it cannot do is demand information outside the scope of the inquiry, ignore a valid appeal, or bypass the legal procedures that govern its investigative powers.
Your rights during a compliance check include the right to professional representation at every stage, the right to challenge HMRC’s findings through an internal review process, and the right to appeal to the First-tier Tax Tribunal if internal resolution fails. Those rights are real and exercisable using them is not confrontational, it is appropriate.
Compliance Check Risk Assessment
| Situation | Risk Level |
| Complete, organised records | Low |
| Minor discrepancies with explanation | Low–Medium |
| Missing documentation for some transactions | Medium |
| VAT inconsistencies across periods | High |
| Unexplained income or transactions | High |
| Multiple filing errors over several years | High |
When Professional Support Becomes Valuable?
Most compliance checks are manageable for businesses with clean records and a clear understanding of what HMRC is asking. The situation changes when the review covers multiple years, when significant tax is potentially at stake, when the business operates in a sector HMRC targets specifically, or when an initial compliance check begins to look like it is heading toward something more formal.
Engaging experienced tax investigation advisors at that point rather than after the situation has developed further provides structured communication management, evidence preparation, penalty mitigation where applicable, and representation through any appeal process. The practical value of that support, measured in reduced penalties and shorter timelines, typically substantially exceeds its cost.
Frequently Asked Questions
My business always files on time and pays correctly. Why would HMRC still select me?
Because selection is not always about suspicion. HMRC cross-references data from banks, digital platforms, and third-party sources against your returns. A mismatch even caused by timing differences can trigger a check regardless of your compliance history. Sector campaigns are another route: if HMRC targets a particular industry, businesses within it may be reviewed simply because of their sector classification.
How long should a business retain financial records in case HMRC requests them?
Companies must keep records for at least six years from the end of the relevant accounting period. Sole traders need at least five years after the 31 January filing deadline for the relevant tax year. Digital records are acceptable and often easier to retrieve than paper. The key principle: if HMRC asks for documentation and you cannot produce it, the burden of proof shifts significantly against you.
Can HMRC visit my business premises, and do I have to allow it?
HMRC has the power to conduct visits, but most compliance checks involve written correspondence rather than physical inspections. Where a visit is proposed, you have the right to agree a suitable time, have a representative present, and clarify the scope beforehand. Accepting a visit without establishing those terms in advance is one of the more common mistakes businesses make.
If an error is discovered during a compliance check, should I disclose it or wait for HMRC to find it?
Disclose it. HMRC’s penalty framework explicitly distinguishes between voluntarily disclosed errors and those it discovers independently; penalties for proactive disclosure are considerably lower. Waiting to see whether HMRC finds the error, and then addressing it defensively, typically results in higher penalties and a longer process.
My accountant prepared the returns under review. Does that shift responsibility away from my business?
No. Legal responsibility sits with the taxpayer who submitted the return, not the preparer. That said, relying on a qualified professional in good faith may influence how HMRC categorises the error innocent versus careless which directly affects the penalty level. Any negligence claim against your accountant is entirely separate from your obligations to HMRC.
Conclusion
An HMRC compliance check is manageable when handled properly. Good records create confidence, early action prevents complications, and understanding your rights means you engage with the process rather than being overwhelmed by it.
Lanop Business and Tax Advisors works with UK businesses at every stage reviewing records before HMRC makes contact, managing correspondence, preparing evidence, and representing clients through enquiries and appeals.
Having the right support early rather than late consistently produces better outcomes. Lanop Business and Tax Advisors is here to protect your business before the problem develops, not after.

What if the best way to develop employees is not to control them, but to support their growth? Strong leaders create workplaces where people feel heard, trusted and encouraged to improve. ILM Level 3 can help aspiring managers build practical skills for guiding and supporting employees effectively. Servant Leadership takes this approach further by placing employee needs and development at the centre of leadership. It encourages leaders to listen, coach and create meaningful opportunities for growth.
In this blog, we will explore the role of Servant Leadership in employee development.
How Servant Leadership Turns Employee Potential into Progress
Below are the key roles Servant Leadership plays in supporting employee growth and professional development:
Creates a Supportive Work Environment
When workers feel free to voice problems and ask questions, they grow more quickly. By paying close attention and treating staff members with respect, servant leaders foster this atmosphere. They concentrate on comprehending what individuals require in order to function and develop.
Employees who work in a supportive environment are also more receptive to learning. They are more open to asking for advice and taking on new tasks. The management skills developed through ILM Level 3 can also help leaders understand how to provide effective workplace support.
Encourages Continuous Learning
Once an employee is aware of their current function, they should continue to learn. People are inspired to continue expanding their knowledge and skills by servant leaders. They might recommend instruction, opportunities for hands-on learning, or difficult assignments.
This emphasis on ongoing education helps staff members get ready for further responsibility. Additionally, it keeps their expertise current as working demands evolve. Employees can advance in their careers steadily when learning is integrated into daily tasks.
Provides Meaningful Coaching and Feedback
Employees receive clear guidance for improvement when they receive positive comments. Servant leaders do more than just call attention to errors. They help staff members understand how to achieve that change by outlining what can be improved.
Frequent employee feedback also helps people see their abilities more clearly. Coaching conversations can be used by leaders to pinpoint areas for improvement and establish realistic objectives. ILM Level 3 can help managers strengthen the communication and leadership skills needed to support such conversations.
Identifies Individual Strengths
Each member of a team contributes unique skills. Rather than treating everyone equally, servant leaders take the effort to identify their strengths. They watch how workers operate and where they are most productive.
Leaders are able to offer appropriate growth chances when they are aware of each person’s strengths. Workers can take on assignments that help them build new skills while strengthening their current ones. This individualised strategy increases the effectiveness and significance of talent development.
Develops Future Leaders
When workers acquire real-world experience, their leadership growth is strengthened. Team members are given the chance to oversee duties and participate in decision-making by servant leaders.
Employees gain an understanding of accountability and teamwork from these encounters. Additionally, they acquire critical leadership abilities including accountability and communication. ILM Level 3 can support the development of practical management skills that help professionals prepare for greater workplace responsibilities. Organisations can develop a more robust internal pool of workers who are prepared for leadership roles in the future.
Strengthens Trust Between Leaders and Employees
Honest communication is necessary for development. Workers must be at ease talking about challenges and areas in which they require assistance. By listening intently and maintaining polite conversation, servant leaders foster trust in the workplace.
Conversations on development are more fruitful when there is strong trust. Workers are free to talk about their professional aspirations. Based on those objectives, leaders can then offer pertinent advice and opportunities.
Encourages Greater Employee Engagement
When individuals are aware that their development is important to their company, they are frequently more engaged. Servant leaders acknowledge the contributions of their staff members and genuinely care about their advancement.
Increased employee engagement may motivate people to take an active role in workplace education. They become more open to accepting responsibility and exchanging opinions. Both individual growth and improved team performance are supported by this involvement.
Promotes Collaboration and Knowledge Sharing
Formal training is not the only way that employees are developed. Through regular cooperation, people might pick up useful talents from their coworkers. Employee support and knowledge sharing are encouraged by servant leaders.
As a result, learning becomes a shared responsibility in a collaborative workplace. While diverse viewpoints enable everyone to generate new ideas, seasoned workers can mentor more junior team members. Sharing knowledge can improve the team’s overall performance.
Connects Personal Growth with Organisational Goals
When personal goals align with broader organisational objectives, employee growth becomes more useful. Servant leaders assist staff members in realising how their growth affects the success of the team and the organisation.
They are able to recognise abilities that are advantageous to the company and the worker. This supports workforce needs and makes career development pathways clearer. Workers are able to comprehend the potential outcomes of their learning and perceive a more compelling reason for it.
Conclusion
Employee development becomes more meaningful when leadership focuses on people rather than authority. Servant Leadership creates opportunities for learning and personal growth while strengthening workplace trust.
For professionals looking to strengthen their leadership skills, Oakwood International provides learning opportunities that can support practical management knowledge and help leaders create workplaces where employees are encouraged to learn, contribute and grow.
Anyone weighing a financial risk management exam wants one thing first: real numbers, not marketing talk. GARP does not sugarcoat this credential, and neither should any guide that claims to prepare you for it. This article breaks down actual pass rates, why the exam feels tough even to trained professionals, and how to structure your study calendar for 2026.
What the FRM Certification Actually Involves
The FRM certification is a two-part exam administered by the Global Association of Risk Professionals (GARP). Part 1 has 100 multiple-choice questions across four hours, and Part 2 has 80 questions in the same time frame. Over 97,000 professionals across 190-plus countries hold this designation, working in banks, asset management firms, and regulatory bodies.
There are no entry barriers for registration. Anyone can sit for Part 1 regardless of degree or work background. The two-year work experience requirement only applies once you clear both exams and want the actual certificate.
FRM Exam Structure at a Glance
- Part 1: 100 questions, 4 hours, covers risk foundations, quant analysis, financial markets, and valuation models
- Part 2: 80 questions, 4 hours, applies Part 1 concepts to market, credit, operational, and liquidity risk
- Offered three times yearly: May, August, and November
- Fees run from USD 1,000 to 1,200 per part depending on registration timing
FRM Certification Exam Pass Rates: The Real Numbers
Candidates researching the financial risk management exam often assume the pass rate mirrors a school test. It does not work that way here. GARP does not curve results against other test-takers; each candidate either clears a set standard or doesn’t.
The November 2025 Part 1 pass rate came in at 47 percent, according to GARP. Historically, Part 1 pass rates have sat in the mid-40s percent range across recent sittings, with a decade-long average close to 46 to 48 percent. Part 2 tends to run higher.
Part 1 vs Part 2 Pass Rate Comparison
| Exam Part | Typical Pass Rate Range | 10-Year Average |
| Part 1 | 41% to 51% | ~46% to 48% |
| Part 2 | 50% to 63% | ~55% to 58% |
Part 2 pass rates dipped to around 50 percent in May 2021 during the shift from paper-based to computer-based testing, but have since settled back into the 54 to 59 percent band, matching pre-pandemic patterns. The November sitting usually edges out May slightly, largely because it includes more repeat candidates who already know their weak spots.
Why Part 2 Looks Easier Than It Is
A higher pass rate for Part 2 does not mean lighter content. Candidates who reach Part 2 are already a filtered, more committed group, and the actual material, covering Basel norms, credit derivatives, and model validation, runs deeper than Part 1. Treat the second exam with the same seriousness, not less.
Why the FRM Certification Feels Harder Than It Looks
On paper, a pass rate near 50 percent doesn’t sound brutal. But FRM candidates are usually already numerate working professionals who prepare with intent, and roughly half of them still don’t clear the bar. That tells you the difficulty sits in the applied nature of the questions, not in obscure trivia.
The financial risk management exam leans heavily on calculation under time pressure rather than definition recall. You are asked to apply formulas to scenarios you haven’t seen phrased that exact way before.
Topics That Trip Up Most Candidates
- Valuation & Risk Models and Financial Markets & Products together carry 60 percent weight in Part 1, and both demand strong quantitative footing
- Quantitative Analysis punishes anyone who skipped statistics or probability basics
- Part 2’s operational risk and liquidity sections require reading dense regulatory material, not just memorizing numbers
- Time management within the four-hour window often costs more marks than actual knowledge gaps
Study Hours Candidates Actually Put In
GARP reports candidates typically invest around 240 hours per part over several months, though this swings widely based on background. Someone with a finance or engineering degree may need less; someone new to markets and statistics should plan for the higher end, sometimes past 300 hours.
Building a 2026 Prep Strategy for the FRM Certification
Remaining 2026 windows for both parts fall in August and November, giving candidates a workable runway if they start now. Most people finish both parts within 10 to 15 months when sitting for consecutive or near-consecutive windows.
A realistic plan for the financial risk management exam splits into three phases:
- Foundation phase (8 to 10 weeks): Read through the full curriculum once, topic by topic, without rushing. Build formula sheets as you go instead of at the end.
- Practice phase (6 to 8 weeks): Begin full-length mock exams under timed conditions, since candidates who complete four to six mocks consistently outperform those who only read notes.
- Review phase (2 to 3 weeks): Revisit weak topic areas flagged by your mock scores, redo flashcards, and run one final timed mock close to exam day.
Practical Tips That Move the Needle
- Prioritize Financial Markets & Products and Valuation & Risk Models early since they carry the heaviest weight
- Use only GARP-approved calculators, either the TI BA II Plus or HP 12C, and practice with the same one you’ll bring on exam day
- Track your mock scores by topic rather than an overall percentage, so you know exactly where to spend the last few weeks
- Register early for each window since fees rise after the early deadline passes
Is the FRM Certification Worth the Effort in 2026
Given the pass rates and hour commitment, some candidates ask whether the financial risk management justifies the grind. For anyone aiming at roles in market risk, credit risk, or regulatory reporting at banks and asset managers, the designation still opens doors that generic finance degrees don’t. The exam’s difficulty is exactly why employers weigh it seriously; a credential that everyone clears easily wouldn’t carry the same signal.
Zell Education works with candidates preparing for the FRM certification through structured study plans, doubt-resolution sessions, and full-length mock tests that mirror actual exam pressure. Pairing a real study calendar with consistent practice is what separates candidates who clear the exam from those who repeat a sitting.
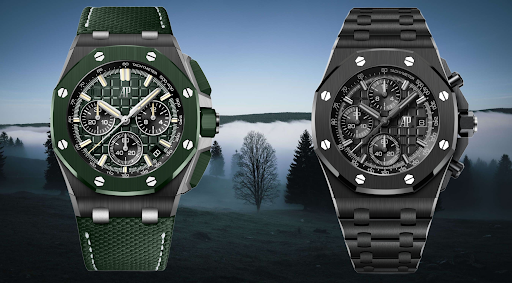
The Audemars Piguet Royal Oak and Royal Oak Offshore share the same unmistakable octagonal design language, but they offer very different wearing experiences. The Royal Oak is generally slimmer, more refined and closely connected to the original 1972 luxury sports-watch concept. The Royal Oak Offshore, introduced in 1993, takes that design in a larger, more muscular and sport-focused direction.
For most buyers, the decision comes down to presence and versatility. Choose the Royal Oak if you want an elegant integrated-bracelet watch that can move easily between casual and formal settings. Choose the Royal Oak Offshore if you prefer a bigger case, stronger wrist presence, chronograph-focused styling and a more contemporary sports-watch character.
AP Offshore vs Royal Oak at a Glance
| Feature | Royal Oak | Royal Oak Offshore |
| First introduced | 1972 | 1993 |
| Original designer | Gérald Genta | Emmanuel Gueit |
| Overall style | Refined luxury sports watch | Bold performance-oriented sports watch |
| Case presence | Slimmer and more restrained | Larger and more muscular |
| Dial style | Clean, architectural | Busier and more aggressive |
| Signature pattern | Tapisserie / Grande Tapisserie | Often Méga Tapisserie |
| Bracelet/strap | Famous integrated bracelet | Frequently rubber strap; bracelet options also exist |
| Chronographs | Available | Central to the collection |
| Best for | Versatility, heritage, understated luxury | Strong wrist presence and sporty styling |
Royal Oak and Royal Oak Offshore Are Not the Same Watch
The Offshore is part of the wider Royal Oak family, but it should not be treated simply as a larger version of the Royal Oak.
The original Royal Oak appeared in 1972. Designed by Gérald Genta, it challenged traditional ideas of luxury watchmaking by using hand-finished stainless steel, an exposed octagonal bezel, visible screws, an integrated bracelet and a patterned dial. Audemars Piguet describes the model as a watch that helped redefine the codes of Haute Horlogerie.
More than two decades later, Audemars Piguet introduced the Royal Oak Offshore in 1993. Designer Emmanuel Gueit retained the Royal Oak DNA but exaggerated almost every visual element. Its oversized proportions, exposed rubber gasket and powerful appearance earned the original model the nickname “The Beast.”
That difference in philosophy is still visible today.
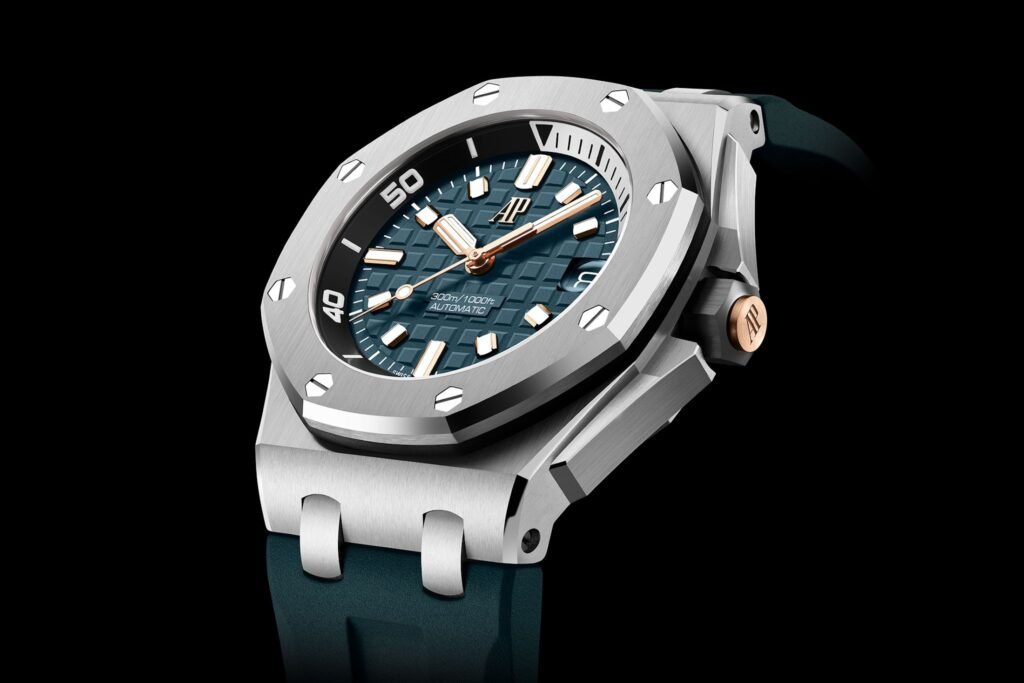
Design: Refined Royal Oak or Aggressive Offshore?
Put the two watches next to each other and the family resemblance is obvious.
Both use the familiar octagonal bezel and exposed screws. Both retain the geometric case architecture that makes an Audemars Piguet recognizable from across a room.
The difference is in how those features are presented.
A) Royal Oak
- The Royal Oak emphasizes proportion and finishing. Its case, bezel and bracelet flow together as one design, with alternating brushed and polished surfaces creating much of the visual interest.
- Models such as the current 41 mm Royal Oak Selfwinding maintain the clean proportions and integrated construction associated with the collection.
- It feels luxurious without needing excessive thickness or visual complexity.
B) Royal Oak Offshore
- The AP Offshore deliberately pushes the design further.
- Its cases typically have more volume, while elements such as the crown guards, pushers, rubber components, oversized numerals and chronograph subdials create a much more technical appearance.
- Audemars Piguet continues to describe the Offshore as the bold and robust side of the Royal Oak family.
- If the standard Royal Oak looks architectural, the Offshore looks engineered.
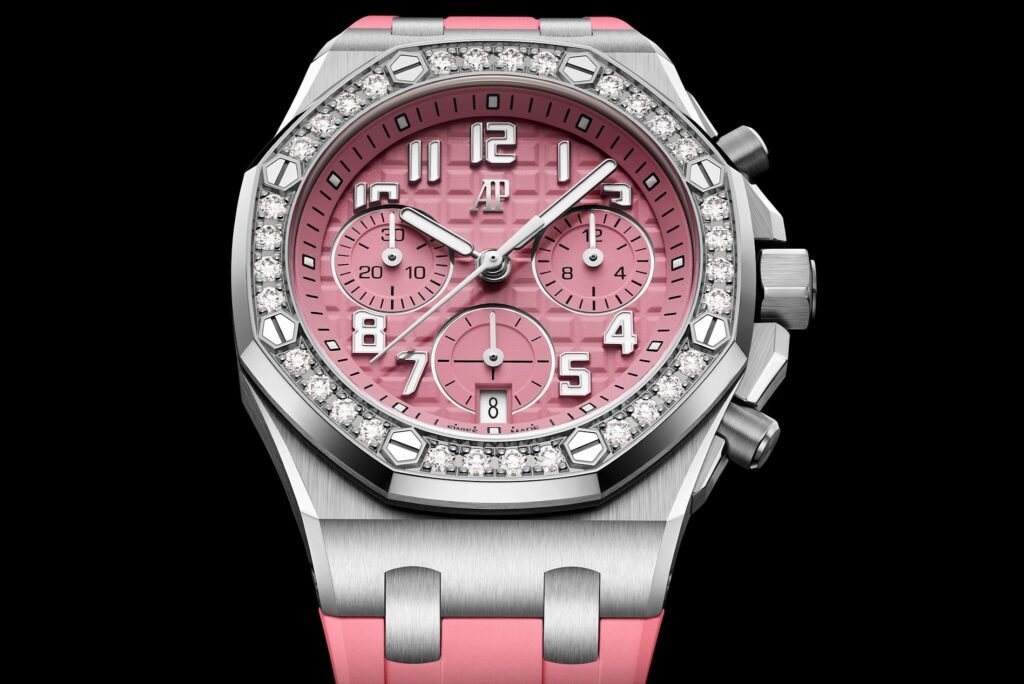
Size and Wrist Presence
Size is one of the biggest practical differences in the AP Offshore vs Royal Oak comparison.
The Royal Oak collection spans several dimensions, including compact models and larger 41 mm references. A 41 mm Royal Oak can still have significant wrist presence because the integrated bracelet and case shape make it wear differently from a conventional round watch.
The Offshore has historically been associated with larger dimensions. That remains an important part of its personality, although the modern collection is more diverse than many buyers realize.
For example, Audemars Piguet introduced new 37 mm Royal Oak Offshore Selfwinding Chronographs for 2026, showing that an Offshore no longer automatically means an extremely large case.
Even so, comparable Offshore models generally feel more substantial because of their thicker construction and more prominent case details.
Choose by Wrist, Not Just Case Diameter
Case diameter alone does not tell you how an AP will wear.
Consider:
- Case thickness
- Lug-to-lug feel
- Integrated bracelet geometry
- Strap flexibility
- Wrist circumference
- Weight
- How much wrist coverage you prefer
Someone comfortable with a 41 mm conventional watch may find a 41 mm Royal Oak considerably more noticeable.
Trying the watch on is particularly valuable before choosing between these two collections.
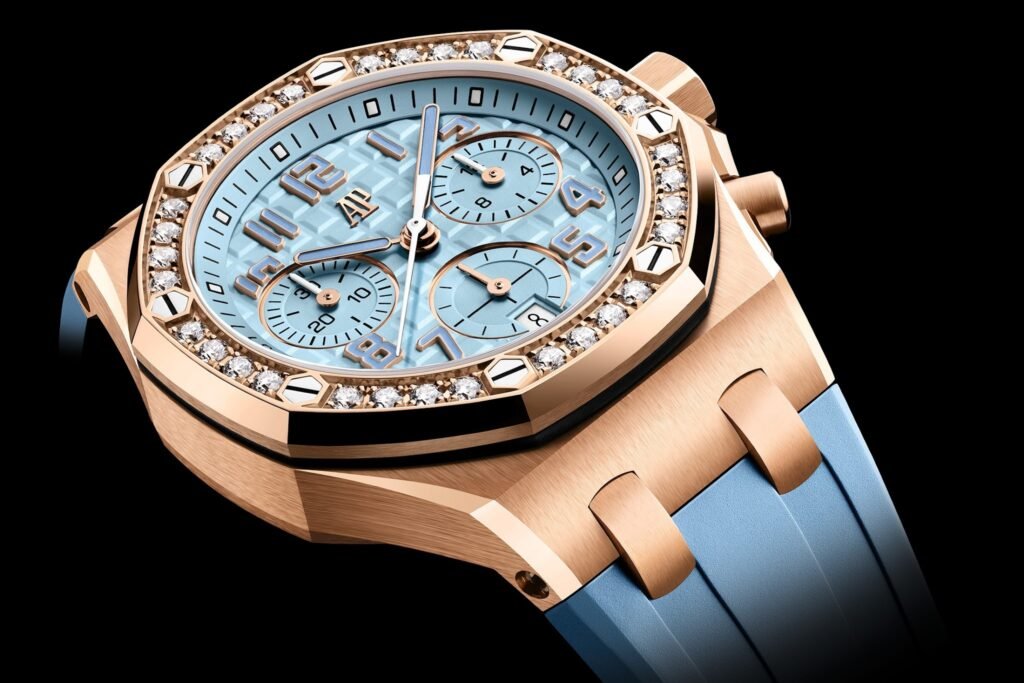
Dial Differences
The dial is another easy way to distinguish the Royal Oak from the Offshore.
The Royal Oak is known for its textured Tapisserie dials, including the famous Grande Tapisserie pattern found on contemporary references. Audemars Piguet continues to use this pattern on models such as the 41 mm Royal Oak Selfwinding.
Its layout is usually relatively restrained, particularly on time-and-date versions.
The Royal Oak Offshore often uses a larger-scale Méga Tapisserie treatment combined with oversized Arabic numerals, bold hands and chronograph counters. Current Offshore models continue this more expressive design language.
This produces two very different impressions:
- Royal Oak: texture becomes part of the finishing.
- Offshore: texture becomes part of the visual statement.
Bracelet vs Rubber Strap
The integrated bracelet is one of the strongest reasons collectors are attracted to the Royal Oak.
Rather than looking like a separate component attached to a watch case, the Royal Oak bracelet appears to continue directly from the case. Its finishing and articulation are fundamental parts of the design.
The Offshore takes a more flexible approach.
Rubber straps have become strongly associated with the collection and reinforce its sportier identity. Current Offshore releases continue to use interchangeable rubber straps, while other references have appeared with bracelets and different strap materials.
For buyers deciding between them:
- Integrated bracelet: Royal Oak has the stronger visual identity.
- Rubber strap: Offshore feels more natural and casual.
- Sportier wardrobe: Offshore usually integrates more easily.
- Smart or formal clothing: Royal Oak is generally easier to pair.
Movement and Complications
There is no simple winner here because both collections contain everything from relatively straightforward automatic watches to highly complicated Haute Horlogerie pieces.
The standard Royal Oak range includes selfwinding models, chronographs, perpetual calendars, flying tourbillons and other high complications. The contemporary collection even includes Grande Complication references.
The Offshore is particularly closely associated with the chronograph.
Its larger case architecture naturally suits multiple subdials, pushers and sport-oriented displays. In 2026, Audemars Piguet introduced the Calibre 6401 in new 37 mm Offshore chronographs. The integrated automatic column-wheel chronograph uses a patented vertical clutch and offers a 55-hour power reserve.
The important point is therefore not that one collection has “better” movements.
Instead, choose the specific reference according to the complication you actually want.
Which AP Is More Comfortable?
For most wrists, the Royal Oak has the advantage when all-day comfort is the priority.
Its comparatively restrained proportions and integrated construction make it suitable for situations where a thick sports watch may become intrusive.
The Offshore intentionally provides more physical presence. Buyers who enjoy feeling a substantial mechanical watch on the wrist may actually prefer this.
Comfort therefore depends on preference rather than specifications alone.
If you regularly wear fitted shirt cuffs or formal clothing, the Royal Oak is normally easier to accommodate.
If you usually wear polos, T-shirts, casual tailoring or sportswear, the Offshore’s additional thickness is less likely to be an issue.
Which Looks More Luxurious?
Both are high-end Audemars Piguet watches, but they communicate luxury differently.
The Royal Oak’s luxury comes primarily from:
- Case and bracelet finishing
- Precise proportions
- Dial texture
- Integrated construction
- Historical significance
The Offshore communicates it through:
- Larger dimensions
- More complicated visual layouts
- Contrasting materials
- Bold case architecture
- Stronger wrist presence
The Royal Oak can therefore appear more understated, even though it remains immediately recognizable to watch enthusiasts.
The Offshore rarely tries to disappear.
Which Is More Versatile?
The Royal Oak wins for overall versatility.
A steel Royal Oak can work with jeans, business clothing, evening wear or relatively formal outfits without appearing completely out of place.
The Offshore occupies a more specific aesthetic territory. It excels as a casual luxury sports watch but can feel oversized with traditional formal clothing.
That does not make the Offshore less desirable. It simply means that its design makes a stronger statement.
If you plan to own only one Audemars Piguet, the Royal Oak is usually the easier watch to use across different situations.
Which Has More Heritage?
The Royal Oak has the stronger historical claim.
Its 1972 launch came first, and the model became one of the defining designs of modern luxury sports watches. Audemars Piguet credits Gérald Genta’s design with challenging traditional watchmaking conventions through its stainless-steel construction, integrated bracelet and distinctive octagonal form.
The Offshore nevertheless has substantial history of its own.
Launched in 1993, it has now existed for more than three decades and played an important role in the rise of oversized luxury sports watches. Its association with “The Beast” and its distinctly 1990s design philosophy give it an identity independent of the original Royal Oak.
Collectors interested primarily in the origin of the design will probably favor the Royal Oak.
Collectors interested in the evolution of that design may find the Offshore more interesting.
Royal Oak Offshore vs Royal Oak for Collectors
Neither collection is automatically the better collectible.
Reference, production period, condition, material, dial, originality, documentation and rarity can matter far more than whether “Royal Oak” or “Offshore” appears on the model name.
The Royal Oak tends to appeal to collectors who prioritize:
- Iconic design history
- Integrated bracelets
- Classic proportions
- Fine finishing
- Long-term versatility
The Offshore attracts collectors interested in:
- Larger statement watches
- Chronographs
- Unusual materials
- Limited editions
- Distinctive color combinations
- Sport-oriented AP designs
Vintage and discontinued references can also behave very differently from current-production watches, so individual references should always be evaluated separately.
AP Offshore vs Royal Oak: Which Should You Buy?
Choose the Royal Oak if you want the purest expression of Audemars Piguet’s iconic sports-watch design.
It is especially suitable if you value an integrated bracelet, thinner proportions, versatility and the strongest connection to the original 1972 Royal Oak.
Choose the Royal Oak Offshore if you want more visual impact.
Its larger construction, prominent chronograph design, rubber straps and stronger use of contrasting materials make it particularly appealing to buyers who want their AP to feel unmistakably sporty.
Best for Different Buyers
Choose Royal Oak for:
- Everyday luxury
- Business and smart-casual wear
- Integrated-bracelet design
- Classic AP styling
- More restrained proportions
Choose Royal Oak Offshore for:
- Bigger wrist presence
- Casual and sports-focused outfits
- Chronograph enthusiasts
- Rubber straps
- More aggressive AP styling
Final Verdict
The difference between the Royal Oak and Royal Oak Offshore is less about quality and more about personality.
The Royal Oak is the cleaner, more refined and historically significant choice. Its integrated design has remained remarkably recognizable since the original watch appeared in 1972.
The Royal Oak Offshore is the louder and sportier interpretation. Since 1993, it has taken the fundamental Royal Oak shape and amplified it with stronger proportions, chronograph layouts and more adventurous materials.
For maximum versatility, the Royal Oak is difficult to beat. For maximum wrist presence, the Offshore has the advantage.
The right AP is ultimately the one whose proportions, design and character make the most sense on your wrist.
Frequently Asked Questions
1.Is the Royal Oak Offshore bigger than the Royal Oak?
Generally, yes. The Offshore has traditionally used thicker and more substantial cases, although the collection now includes smaller options such as 37 mm chronographs. The exact comparison depends on the references being considered.
2.Is the Royal Oak Offshore a Royal Oak?
Yes. The Royal Oak Offshore belongs to the wider Royal Oak family but was developed as a bolder interpretation of the original design. It was launched in 1993, 21 years after the original Royal Oak.
3.Who designed the Royal Oak Offshore?
The Royal Oak Offshore was created by Emmanuel Gueit. The original Royal Oak was designed by Gérald Genta.
4.Is the Royal Oak or Offshore better for everyday wear?
The Royal Oak is generally easier to wear every day because of its slimmer and more versatile design. The Offshore can still be an everyday watch for buyers who prefer larger, sportier pieces.
5.Which is more formal, Royal Oak or Royal Oak Offshore?
The Royal Oak is generally the more formal of the two. Its cleaner dial, integrated bracelet and slimmer proportions allow it to work more naturally with smart and business clothing, while the Offshore has a stronger casual and sporting character.
6.Is the Royal Oak Offshore only available as a chronograph?
No. Chronographs are strongly associated with the Offshore, but the family has included other configurations, including the Royal Oak Offshore Diver. The available references vary over time.

Complex Tech Ideas Need Clear Context Before They Become Short Videos

7 Practical Things to Consider When Choosing a Watch Winder for a Breitling

The 6 Best CNC Machining Services in 2026 (Ranked for Speed, Precision & Scalability)
Who Is Shameera? All You Need To Know About Charli XCX’s Mother
Who Is Gulliver Flynn Oldman? The Untold Story of Sir Gary Oldman’s Son
Meet Rosemary Turner: The Mother of Actor Callum Turner
-
Biographies7 months ago
Who Is Shameera? All You Need To Know About Charli XCX’s Mother
-
Biographies6 months ago
Who Is Gulliver Flynn Oldman? The Untold Story of Sir Gary Oldman’s Son
-
Biographies7 months ago
Meet Rosemary Turner: The Mother of Actor Callum Turner
-
 Biographies5 months ago
Who is Alexandra James? Inside The Life of Jeremy Clarkson’s Former Partner
-
 Biographies7 months ago
Who is Todd McRae? Meet Tate McRae’s Father
-
 Biographies6 months ago
Who Is Daniel Mara? The Untold Story of Kate Mara’s Private Sibling
-
 Celebrity7 months ago
Who Is Peter Hernandez? The Real Story of Bruno Mars’ Father
-
 Biographies7 months ago
Who Is Alvin Martin? All About the Whoopi Goldberg’s First Husband